You’ve got $800 a month left after bills. Your credit card charges 24% interest. The stock market has averaged about 10% a year for a century. Your Portland friend swears by maxing out investments; your Seattle coworker says kill the debt first or you’re an idiot. Who’s right? The debt-vs-investing question is personal finance’s most argued trade-off, and in the Pacific Northwest — with its high housing costs, tech salaries, and outdoor-everything lifestyle pulling at your wallet — getting it wrong costs real money. Here’s the framework that actually settles it.
The Only Math That Matters: Compare the Rates
Strip away the philosophy and it’s arithmetic. Every dollar you put toward debt “earns” you the debt’s interest rate, guaranteed and tax-free. Every dollar you invest earns the market’s return, uncertain and variable.
- Debt at 20%+ (credit cards, payday loans): Pay it off. Full stop. No investment reliably beats a guaranteed 24% return, because paying off a 24% card is a guaranteed 24% return. This isn’t a debate; it’s math.
- Debt at 7–10% (personal loans, some auto loans): Lean toward paying it off, but it’s a judgment call. The market probably beats 8% over long periods, but “probably over decades” doesn’t help if the debt stresses you monthly.
- Debt at 4–6% (mortgages, federal student loans): This is the genuine toss-up zone. Historical market returns beat these rates, but with volatility. Most financial planners suggest splitting: minimum debt payments plus steady investing.
- Debt under 4%: Minimum payments, invest the rest. Money is cheap; let compounding work.
The SEC’s Investor.gov offers excellent primers on expected market returns versus guaranteed returns — the core concept being that debt payoff is the only “investment” with a truly guaranteed yield.
The Exceptions That Override the Math
Math gives you the baseline; these situations override it:
Exception 1: The 401(k) match (always take it)
If your employer matches 401(k) contributions, contribute enough to get the full match before accelerating any debt payoff — even 24% credit card debt. A 50% or 100% instant match is a 50–100% immediate return, which beats everything. This is free money with an expiration date; debt will wait.
Exception 2: No emergency fund
Before either aggressive debt payoff or investing, build a starter emergency fund of $1,000–$2,000 (one month of expenses is the real target). Without it, every car repair or medical bill goes right back onto the credit card, and you’ve run in a circle. The CFPB’s savings resources show that even small cash buffers dramatically reduce reliance on high-cost debt.
Exception 3: The debt is crushing your monthly cash flow
Math says invest while making minimums on 5% debt. But if minimum payments consume 40% of your income and you’re one emergency from disaster, the psychological and practical value of killing a monthly payment can outweigh the spreadsheet. Financial stress has real health costs — that’s not irrational, it’s data.
The Pacific Northwest Wrinkles
Regional realities shift the standard advice:
- Housing costs compress the choice. Seattle and Portland rents and mortgages eat 35–45% of median incomes. When housing already strains the budget, the “extra” $800/month in the example is optimistic — many PNW households are really choosing between minimum payments and any investing at all. In that case: match, emergency fund, then highest-rate debt. Investing beyond the match waits.
- Tech compensation is lumpy. RSUs, bonuses, and equity refreshers mean windfalls. Have a rule in advance: 50% of any windfall to highest-rate debt, 30% to investments, 20% to fun. Deciding during the windfall leads to lifestyle inflation.
- The lifestyle tax is real. Ski passes, hiking gear, breweries, and $7 lattes aren’t moral failings — they’re why people live here. But be honest: if “PNW lifestyle” spending is what’s keeping you from either goal, that’s the actual problem, and our guide to saving money on everyday expenses helps find the leaks without killing the joy.
- State taxes are kind. Washington has no income tax; Oregon has no sales tax. Factor your actual state situation into take-home calculations rather than using generic national examples.
The Hybrid Strategy Most People Should Actually Use
For the common case — some credit card debt, some lower-rate debt, a 401(k) with a match — here’s the order of operations:
- Contribute to the 401(k) match. Free money first, always.
- Build a $1,000–$2,000 starter emergency fund. Park it in a high-yield savings account.
- Attack debt above 7% aggressively. Avalanche method (highest rate first) is mathematically optimal; snowball (smallest balance first) wins psychologically. Pick the one you’ll actually follow.
- Split the difference on 4–7% debt. Half toward extra payments, half toward investing (Roth IRA is ideal if eligible).
- Minimums on sub-4% debt, invest the rest. Let cheap money ride.
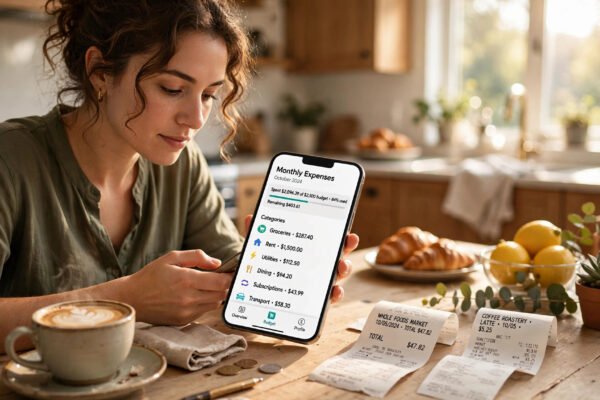
This isn’t as clean as “all debt” or “all investing,” but it’s what survives contact with real life. People who use budgeting tools to track monthly expenses find the hybrid approach easier to automate — set the transfers once, then stop thinking about it.
Conclusion
Deciding between paying off debt and investing in the Pacific Northwest in 2026 isn’t about picking a team — it’s about sequencing. Take the 401(k) match, build a small emergency buffer, kill anything over 7% with prejudice, split the middle zone, and let cheap debt ride while you invest. The people who get this wrong aren’t the ones who pick debt or investing — they’re the ones who pick neither and let the decision paralyze them for years. Run your numbers this week, automate the plan, and get on with enjoying the mountains.
Frequently Asked Questions
Should I pay off credit card debt before investing?
Yes, with one exception: contribute enough to your 401(k) to capture the full employer match first. Beyond that, credit card interest (typically 20–29%) dwarfs any reliable investment return — paying it off is a guaranteed return no investment can match.
What interest rate makes debt payoff better than investing?
As a rule of thumb: above 7%, prioritize payoff; 4–7% is a judgment call (most planners suggest splitting); below 4%, make minimum payments and invest the difference. These thresholds assume long-term market returns around 7–10% with significant volatility.
Should I invest while I have student loans?
Federal student loans typically carry 5–8% rates — the gray zone. The standard advice: take the 401(k) match, build an emergency fund, then split extra money between loan prepayment and investing (especially Roth IRA contributions, which have annual deadlines you can’t get back).
Does the avalanche or snowball method work better?
Avalanche (highest interest first) saves more money mathematically. Snowball (smallest balance first) works better psychologically because quick wins build momentum. Studies suggest the best method is the one you stick with — choose based on honest self-knowledge.
How does living in the Pacific Northwest change this decision?
High housing costs mean less free cash flow, making the emergency fund and high-rate debt payoff relatively more urgent. Lumpy tech compensation argues for pre-committed windfall rules. Washington’s lack of income tax slightly increases take-home pay available for either goal.
Should I pause investing entirely while paying off debt?
Not necessarily — and usually not completely. Always capture the full 401(k) employer match (it’s an instant 50–100% return that beats any debt payoff), and keep any automated retirement contributions that you’d struggle to restart later. Beyond that, directing extra cash toward high-interest debt while maintaining minimum investments is the balanced approach most planners recommend. The danger isn’t splitting your focus — it’s the all-or-nothing thinking that leads to pausing investments for three years, missing irreplaceable compounding time and tax-advantaged contribution windows you can never get back.