
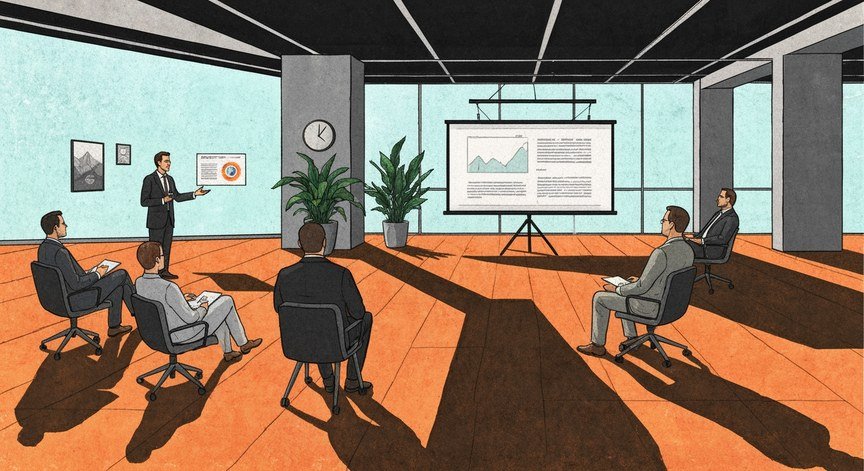
You’ve rehearsed for weeks. Your deck is beautiful. You walk into the room, deliver the pitch of your life — and hear “we’ll be in touch,” which means no. Welcome to the club: investors reject the vast majority of startup pitches they hear, often over 95%. Understanding why do investors reject most startup pitches isn’t about discouraging you — it’s about fixing the real reasons before your next meeting, because most rejections come down to a handful of predictable, fixable problems.
Here’s the uncomfortable context: professional investors see thousands of pitches per year and fund a handful. They’re not looking for reasons to say yes — they’re pattern-matching for reasons to say no, as fast as possible. Your job isn’t to be perfect; it’s to survive the first five minutes of scrutiny without triggering the automatic filters. Most founders never learn what those filters are.
Why Investors Reject Startup Pitches: The Top Reasons
- No real traction. The #1 killer. “We have no revenue yet, but…” is where most pitches die. Investors fund momentum, not ideas. Even modest traction — $10K MRR, 1,000 active users, three paying pilot customers — changes the conversation completely. If you have no traction, you’re not ready for investors; you’re ready for customers. Go get them first.
- Weak or incomplete team. Investors bet on teams, not ideas. A solo founder with no technical co-founder pitching a tech product, a team with no domain experience, or obvious key hires missing — these are instant concerns. The question in their head: “Can THESE people build THIS?” If the answer isn’t an obvious yes, it’s a no.
- Market too small (or too vague). “The market is $50 billion” means nothing if your reachable segment is tiny. Investors need venture-scale returns, which typically means a credible path to $100M+ in revenue. Niche businesses can be wonderful — they’re just not venture-backable. Know which game you’re playing.
- No defensibility. “What stops a well-funded competitor from copying this in three months?” If your answer is weak, the pitch is over. Defensibility comes from network effects, proprietary data, deep tech, brand, or distribution advantages — not from “we’ll move fast.”
- Unclear business model. If you can’t explain exactly how you make money — pricing, margins, customer acquisition cost vs. lifetime value — in two sentences, investors assume you haven’t figured it out. “We’ll figure out monetization later” worked in 2010. It doesn’t now.
- Unrealistic financials. Hockey-stick projections with no basis in reality insult the investor’s intelligence. They’ve seen ten thousand decks; they know what real growth curves look like. Base projections on actual unit economics and comparable companies, and show you understand the assumptions.
- Founder red flags. Defensiveness about tough questions, inability to admit what you don’t know, badmouthing competitors or former partners, seeming unfocused or running multiple ideas simultaneously. Investors are judging whether they want to work with you for a decade. Character signals matter enormously.
What Investors Actually Want to See
Flip the rejections around, and the winning formula emerges. Investors want: a team with unfair advantages (domain expertise, technical depth, distribution access), traction that proves demand, a large and growing market, a clear path to defensibility, unit economics that work, and founders who are coachable, resilient, and obsessed with the problem.
Notice what’s NOT on the list: a brilliant idea (ideas are cheap), a beautiful deck (it just needs to be clear), or famous advisors (they rarely move the needle). Founders consistently overweight pitch polish and underweight the fundamentals. The best pitch in the world can’t save weak traction; modest traction with an average pitch gets funded regularly.
Also understand the math from their side. A VC fund needs a few massive winners to return the fund — most investments go to zero. They’re not looking for “good businesses” (profitable, stable, growing 20%/year). They’re looking for potential 100x outcomes. That’s why great small businesses get rejected: they’re fundable by banks and angels, not by VCs. If your business is a great $5M/year company but not a potential $500M company, stop pitching VCs and find the right capital — our guide to validating your business idea helps you determine which game you’re actually in.
How to Fix Your Pitch Before the Next Meeting
Practical steps, in priority order:
- Get traction first. Spend the next 90 days selling, not pitching. Every dollar of revenue and every customer changes your leverage more than any deck refinement.
- Lead with the team slide. If your team is strong, put it early. If it’s not, fix the team before pitching — recruit the missing co-founder or key hire.
- Make the market slide specific. Bottom-up sizing (number of customers × price) beats top-down (“1% of a huge market”) every time. Show your wedge: the specific segment you’ll dominate first.
- Address the obvious objection head-on. Whatever the elephant in the room is — competition, regulation, your lack of experience — name it and answer it before they ask. This builds enormous credibility.
- Show you know your numbers. CAC, LTV, churn, burn rate, runway, gross margin. Fluency here signals you’re an operator, not a dreamer.
- Get warm introductions. Cold pitches convert at a fraction of warm intros. Work your network — networking as an entrepreneur isn’t just for customers; investor intros flow through the same relationships.
- Practice with friendly skeptics. Pitch to experienced founders or angels who’ll give brutal feedback before you pitch real targets. The first time you hear a tough question shouldn’t be when money is on the line.
And remember the SBA’s perspective: most small businesses are funded through personal savings, friends and family, bank loans, and revenue — not venture capital. VC is right for a tiny fraction of startups. Make sure you’re chasing it for the right reasons, not just the prestige.
The Bottom Line
Investors reject most startup pitches because of weak traction, incomplete teams, small or vague markets, no defensibility, unclear economics, or founder red flags — not because the idea wasn’t clever enough. The fix is almost always the same: build more, pitch less. Get customers, strengthen the team, sharpen the numbers, then pitch from strength. If venture capital isn’t the right fit for your business model, that’s not failure — it’s clarity. The SEC’s resources on raising capital outline your options objectively. Fundability is a function of fundamentals. Fix the fundamentals, and the funding conversation changes completely.

3 Comments